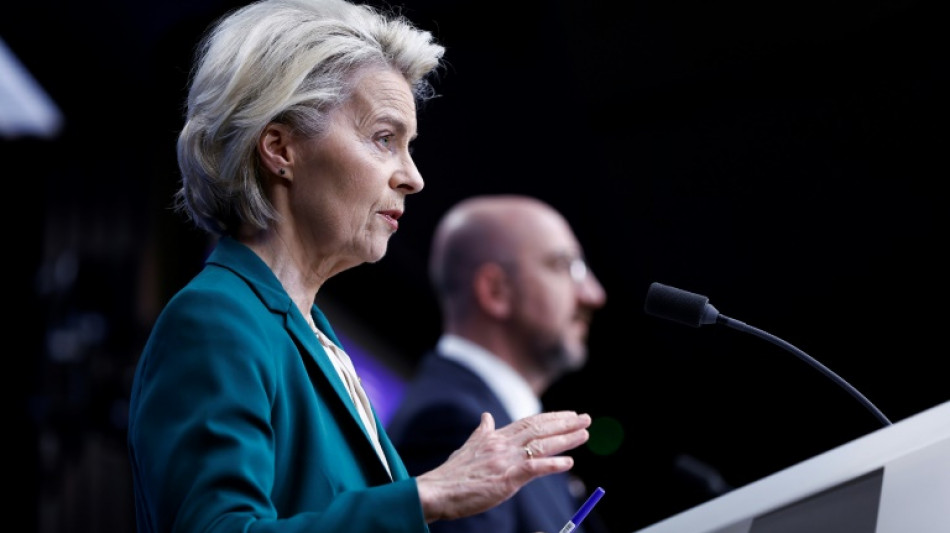
EU seeks to leverage might to confront China, US challenge / Photo: © AFP
 Trump's beef policies irk Texas ranchers, testing their loyalty
 Nvidia, OpenAI CEOs to attend Xi dinner at White House
 Anthropic picks Accenture for in-house AI safety evaluation
 Balogun returns as Monaco beat Lens to continue strong Ligue 1 start
 'Pause' on overt repression in Venezuela, but reforms still needed: HRW
 Global stocks mixed as yen falls despite Bank of Japan rate hike
 Cuba hit with seventh major blackout of the year
 Murray out with concussion so Wentz will start for Vikings
 UN chief 'deeply regrets' US visa refusal to Abbas for annual meeting
 England quick Carse to face no charges over alleged nightclub assault
 Mancini brings nine newcomers into the first squad of his Italy comeback
 Czechs level Davis Cup tie against USA as South Korea eye Finals
 New France boss Zidane confirms Mbappe as captain after naming first squad
 California governor signs order to explore AI 'kill switch'
 Head leads run spree as Australia win Zimbabwe ODI series
 In-form Raphinha wants to finish career at Barcelona
 Warren Buffett steps down as Berkshire Hathaway chairman
 Carrick confident Man Utd can 'work through' tough time
 Mbappe ends Nike partnership to join Swiss brand On
 Liverpool boss Iraola puts Bournemouth love affair on hold
 'A disaster' if Man City do not win says Maresca after flawless start
 Kerry James Marshall: American 'blackness' painter celebrated in Europe
 Spain coach De la Fuente offers 'full support' to people of Ceuta
 Russia seizes assets of Nestle, French firms over West's Ukraine support
 England can build on World Cup 'spirit', says Tuchel
EU leaders gave fresh impetus on Thursday to a controversial project to integrate the bloc's financial markets in a bid to keep pace with China and the United States -- including in the global race to produce clean technology.
The single market has supported the rise of European giants in different industries, from aviation to chemicals to cars. But at more than 30 years old, the European Union agrees on the need for an update.
During a summit in Brussels, EU leaders were told that the time has come to scale up the single market to include the defence, energy, finance and telecoms sectors.
The argument goes that fragmentation in those sectors with divergent national rules hurts the EU's competitivity, at a time when global powers like China and the United States are pouring billions into state aid to prop up their key industries.
Although the EU has a single currency, the status quo means its start-ups cannot raise the jaw-dropping amounts their US rivals can, and Europeans currently find it more rewarding to send more than 300 billion euros of their savings out of the bloc, mainly into US markets, each year.
"That is money missing for the development of our companies and the European Union. And it is due to the fragmentation of our capital markets," European Commission chief Ursula von der Leyen told reporters after the end of the summit.
The idea of integrating the 27 EU member states' markets, however, divides the bloc, and led to several hours of intense discussions between the leaders.
"There was a very long debate because the starting positions are divergent," French President Emmanuel Macron told a press conference.
"The savings and investment union is the key to being able to mobilise private financing for our priorities. Today, we established a method, principles, a timetable. We will return to the subject from June," Macron added.
- 'No time to waste' -
The EU has a population of 450 million and is home to some of the world's biggest economies including Germany and France.
But while less than 15 percent of personal savings remain in US bank accounts, nearly a third of the 35 trillion euros of European savings are untouched.
German Chancellor Olaf Scholz echoed Macron on the need for progress.
"European companies must be able to benefit from the economies of scale offered by such a large European internal market if we want to progress in terms of growth, competitiveness and successfully complete... the green and digital transition," Scholz said.
The clean energy and digital transitions that Brussels has made its priority in the coming years will require additional annual investment of nearly 620 billion euros ($660 billion), according to the European Commission.
But from artificial intelligence to solar panels, from computer chips to batteries, the EU is fast losing ground on innovation to other global powers.
"There's no time to waste. The gap between the European Union and US in terms of economic performances is becoming bigger and bigger," Enrico Letta, the author of a long-awaited report into the single market, told reporters.
Official EU data shows the bloc's economic stagnation has lasted more than 18 months. While the United States grew by 2.5 percent and China by 5.2 percent in 2023, Eurostat data last month showed the EU economy grew by only 0.4 percent.
- 'Radical change' needed -
The debate comes as the EU seeks to define strategic priorities for the European Commission's next five-year mandate following elections across the bloc in June.
While France insists on greater integration, smaller countries have pushed back against a centralised, European supervision of markets being thrust upon them.
Further headaches stem from suggestions to harmonise taxation and bankruptcy regulations at the EU level -- which have thus far faced insurmountable blocks.
"We must avoid over-bureaucratising, over-regulating and over-centralising everything, which some countries are in favour of," Luxembourg Prime Minister Luc Frieden said.
More than half of the bloc's states expressed reluctance on integrating capital markets during the leaders' talks.
Spurring the sense of urgency is the colossal scale of the sums needed: on top of the hundreds of billions required to fund the green transition, as war rages in Ukraine the EU needs tens of billions of euros more to help Kyiv.
Letta's report is not the only one leaders will be leaning on.
Ex-European Central Bank chief Mario Draghi, increasingly touted as a potential successor to von der Leyen, will present his report on the EU single market in the summer.
Draghi gave a taste of what to expect in a speech this week, when he called for "radical change".
T.Bondarenko--BTB