-
 How to Watch the Rugby League World Cup Final on 7plus for Free
-
Women's Asian Champions Trophy 2026 in Bhopal Revives Hockey Legacy
-
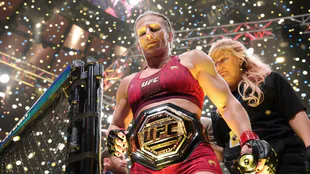 Kayla Harrison Defeats Amanda Nunes via Submission at UFC 334
-
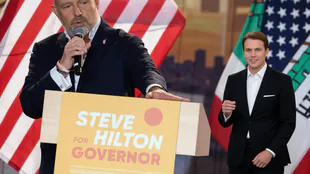
California GOP Faces Near-Extinction After 2026 Midterms; Calls for New Vision
-
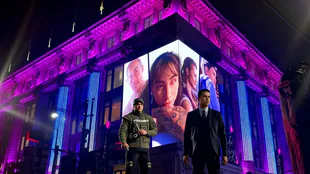 GTA 6 Advertising Strategy and Disc Version Controversy
-
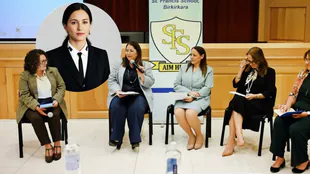
St Francis School Leads €60,000 EU Project to Transform Early Childhood Education
-
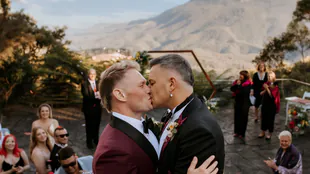 From First Date to Wedding Day: How a TV Quote Sparked a Lifetime Commitment
-
South Africa's Universal Health Coverage Depends on Tackling Poverty and Inequality
-
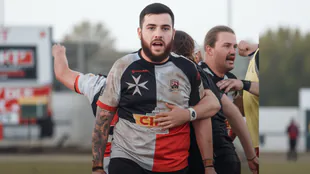 Malta Stuns Sweden with Late Penalty Comeback in Rugby Europe Trophy
-
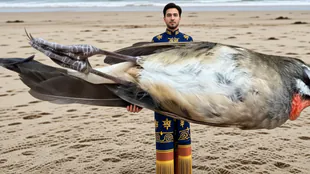
Rare Siberian Rubythroat Dies in UK Garden After Cat Attack
-
 BingX: Major Announcement of Far-Reaching Significance
-
Go Kyung-pyo Drunk Driving Incident Prompts Heavy Editing Across Multiple TV Shows
-
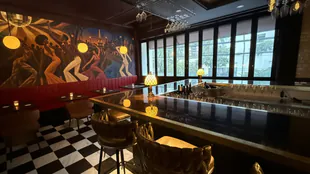 Élan Opens as Late-Night Wine Bar in Honolulu
-
KFF Health News Reporters Discuss ACA Enrollment Challenges, Rising Costs, and Measles Risks
How Swiss Stocks tamed Prices
How Switzerland used equity-backed reserves to keep prices in check - Switzerland’s recent inflation performance is striking by any international standard. While much of the developed world grappled with price rises far above target, Swiss consumer-price inflation has been brought back to muted rates and, at times, hovered close to zero. The country did not stumble upon a miracle cure. Rather, it relied on an institutional playbook that blends a credible inflation target, a strong and freely moving currency—and, crucially, a uniquely structured central‑bank balance sheet in which roughly a quarter of foreign‑exchange reserves is invested in global equities.
At the heart of the Swiss approach lies the exchange‑rate channel. For more than a decade the Swiss National Bank (SNB) accumulated very large foreign‑currency reserves to manage excessive upward pressure on the franc. Those reserves are diversified across currencies and asset classes, with a deliberately significant allocation to equities managed on a passive, market‑neutral basis. Building a portfolio that earns an equity risk premium over time was not an end in itself; it was a way to improve the risk‑return profile of the reserves while maintaining ample firepower for currency operations.
That firepower proved pivotal when global energy and goods prices surged. In 2022 and 2023 the SNB shifted stance and used its reserves in the opposite direction—selling foreign currency to allow a measured appreciation of the franc. A stronger franc lowers the local‑currency price of imported goods and services, damping inflation via “imported disinflation”. Because the reserves had been amassed in earlier years, and because a sizeable slice was in equities that tended to deliver solid returns over time, the central bank could act decisively without jeopardising balance‑sheet resilience.
The portfolio structure also matters for confidence. An equity share—held broadly across markets and sectors, with exclusions on ethical grounds and with no investments in Swiss companies—signals that the reserves are not a dormant hoard but a well‑diversified buffer aligned with long‑run value preservation. When equity markets rose strongly in 2024, gains on those holdings (alongside gold and currency effects) replenished the central bank’s financial buffers. That, in turn, reinforced the credibility of policy at precisely the moment when keeping inflation expectations anchored was most important.
None of this should be mistaken for the SNB “using the stock market” as its primary inflation tool. Monetary policy still rests on an explicit price‑stability objective, a conditional inflation forecast and the policy rate. Indeed, as inflation returned to the target range, the policy rate could be reduced again in 2024–2025. But the equity‑backed reserves shaped the backdrop: they made it easier to tighten monetary conditions through the exchange rate when prices were accelerating, and they underpinned confidence in subsequent easing once inflation receded.
Switzerland’s low and recently near‑zero inflation cannot be ascribed to reserves alone. The country’s energy mix and regulated price components dampened the direct pass‑through from global fuel shocks; the consumption basket assigns a smaller weight to energy than in many peers; and the franc’s safe‑haven status consistently mutes imported price pressures. What distinguishes the Swiss case is how these structural features were complemented by an ample, well‑diversified reserve portfolio—including global equities—that allowed timely foreign‑exchange operations without calling market confidence into question.
The lesson is not that every central bank should load up on shares. Institutional mandates, legal frameworks, market depth and exchange‑rate regimes differ widely. Rather, Switzerland shows that, for a small open economy with a safe‑haven currency, a disciplined, transparent reserve strategy—one that tolerates equity exposure while avoiding conflicts of interest at home—can support the nimble use of the exchange‑rate channel. In the inflation shock of recent years, that combination helped bring prices back under control.
As of late summer 2025, Switzerland’s inflation remains subdued and close to the midpoint of its price‑stability range. The franc is firm, policy is data‑driven, and the central bank’s balance sheet—anchored by highly liquid bonds and a passive equity allocation—retains the flexibility to lean against renewed price pressures or, if conditions warrant, to cushion the economy. Switzerland did not “magic away” inflation by buying shares; it designed a balance sheet that could do its day job when it mattered.
Germany: Migration reform package
DeepSeek: The AI everyone is talking about...
Brazil tests Milei’s gamble
India's island choke point
China’s lithography leap
Hormuz Shock Risk rising
Cuba's golden Goose dies
AI sparks Wall Street panic
EU misstep on mercosur Deal
Argentina reshapes oil
Power at the Heart of Iran