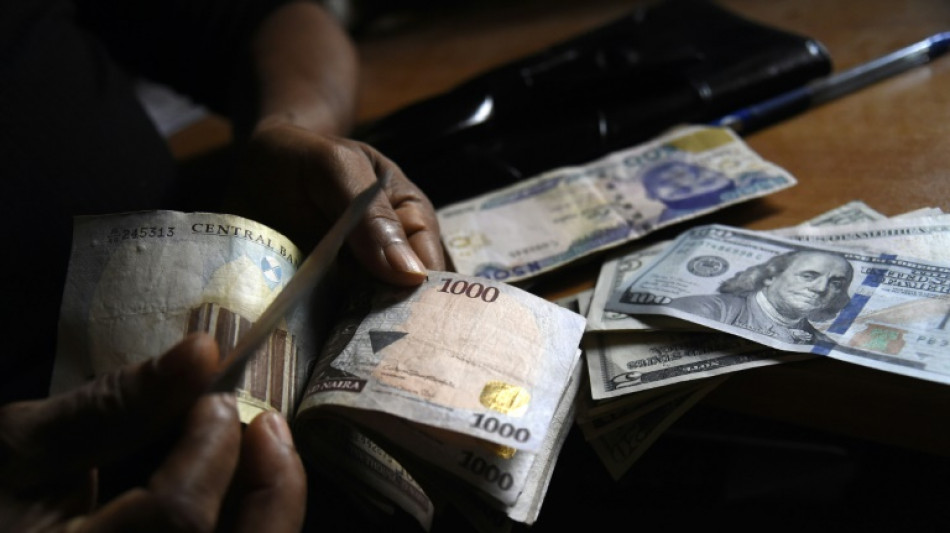
Economic outlook keeps investors wary on Nigeria / Photo: © AFP/File
 Mourinho blasts 'shameless' timing of Vinicius ban decision
 PSG beat Man City in Champions League thriller, Barcola hits Liverpool hat-trick
 US Treasury chief urges stronger IMF role against 'distortionary policies'
 Giant-killers Bodo sink Dortmund in Champions League
 PSG outgun embattled Man City in six-goal Champions League thriller
 In Chicago, pope's hometown, Catholics express shock and support
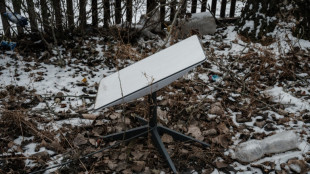 Musk suggests US govt behind any slowdown in Ukraine's Starshield system
 Chiclayo prays for recovery and return of the 'Peruvian pope'
 Barcola scores hat-trick as Liverpool hit LASK for six
 Healthy corals help bleached neighbors regain color: study
 Hope ton helps West Indies level T20 series at 2-2 in India
 Ukraine war reaches shores of Bulgarian fishing village
 Brazil probing 'criminal' origin of forest fires: minister to AFP
 Sally Rooney books cannot be sold in UK amid Palestine Action ban: publisher
 Italian ski stars Goggia and Brignone to miss season opener
 Bournemouth boss Rose urges Cherries to bounce back from Chelsea 'slap'
 Top seed Sabalenka falls at first hurdle in Wuhan
 FX Junction Brings Copy Trading to Everyone, While Their Money Never Leaves With Their Broker
 Brighton defender Struijk's red card overturned
 Saudi league postpones three matches after Houthi attacks
 US consumer inflation up more than expected as midterms loom
 Canadian publisher supports novelist Orelien after AI denial
 Medvedev sees off Tsitsipas to reach Shanghai Masters quarters
 Louvre boss warns of closure risk without major renovations
 Lawes and Genge urge England to end ban on overseas-based players
Record inflation, a sliding naira currency and weak financial structure are keeping investors wary of Nigeria, Africa's largest economy, with some companies even stepping away despite economic reforms under recently-elected President Bola Ahmed Tinubu.
Tinubu, who took office last May, has repeatedly called for patience to allow his reforms to take effect after ending a fuel subsidy and freeing up the naira currency -- policies the government says will bring more foreign investment despite the short-term austerity they cause.
Tinubu's moves have been praised by investors. But they have also led to a sharp fall in the naira's value against the dollar, and access to foreign currency in Nigeria remains a major problem for foreign companies.
For some companies the situation remains too uncertain.
South African supermarket chain Shoprite last week said it was closing its store in Kano, Nigeria's second largest city and capital of the Muslim north, "after careful evaluation of the financial situation of the store and the current business climate".
It was the latest announcement from a foreign company about a reduction in presence in Nigeria despite the potential of a consumer market of more than 200 million people in Africa's most populous nation.
In December, the US multinational Procter & Gamble announced that it would halt production in Nigeria after three decades in the country.
The manufacturer of Pampers, Ariel washing powder and Oral B toothpaste would now import and the company's factory in the southwestern city of Ibadan would close down, and let go of its 1,800 direct and indirect employees.
"When you think about places like Nigeria, when you think about places like Argentina, it's very difficult for us as a US dollar-denominated company to create value," Andre Schulten, P&Gs chief financial officer said at the Morgan Stanley Global Consumer & Retail Conference in New York in December.
"It's also difficult to operate because of the macroeconomic environment."
In August, the British pharmaceutical giant GSK also announced it would end its operations in Nigeria, after more than 50 years working in the country.
"In common with many companies operating in Nigeria, the significant challenge in accessing foreign currency in recent years impacted our local operations and has affected our ability to maintain consistent supply of medicines and vaccines in the market," a GSK spokesman told AFP.
GSK's pharmaceutical products will now be distributed by a third-party company.
- Restructuring -
In more muted ways, other international companies have begun a restructuring of their activities in Nigeria, such as PZ Cussons, a British manufacturer of consumer goods including detergents, soaps, household appliances.
In Nigeria since 1899, the company announced in September its plan to "delist from the Nigerian stock exchange" in order to "simplify" its activities in the country.
"We are focused on mitigating the challenges experienced in the region and we are making progress," the company said.
"It represents an investment in Nigeria and will allow us to simplify and strengthen our business here, putting in place a sustainable structure and platform to maximise long-term growth and value."
In its 2023 annual report, the company noted the fall in the value of the naira affecting its 2024 profits and significantly reduced the value of its liquidity.
For its part, the Dutch-British company Unilever announced in March "changes to its business model" to adapt to market conditions. It said it would abandon two segments -- household products and skin products.
Soon after taking office, Tinubu simultaneously initiated his two major reforms intended to restore public finances and attract foreign investment: the end of fuel subsidies that kept petrol prices artificially low and the liberalisation of the naira.
These measures had immediate effects on the country's economy, including a tripling of fuel prices and an explosion in inflation.
Since May, the naira has lost 41 percent of its value against the dollar on the official currency market and 30 percent on the parallel market, and the price of food has increased by more than 31 percent, according to the World Bank.
Elected on the promise of a programme called "Renewed Hope", Tinubu has repeatedly called for "patience" from Nigerians as those reforms take root.
The reforms were "essential" and were going in the "right direction", according to a World Bank report published in December which stressed that it was time to put in place fiscal and monetary measures in the short and medium term in order to obtain results.
According to the Nigerian Bureau of Statistics (NBS), foreign direct investment (FDI) fell from $1.15 billion in the third quarter of 2022 to $654 million in the third quarter of 2023, representing a decline of about 44 percent.
According to the auditing firm KPMG in an analysis published in January, the departures and restructuring of international companies in Nigeria have "dampened" interest from foreign investors.
But foreign companies are "making a mistake" by leaving the country because Nigeria "has more opportunities than many African countries", Jonathan Aremu, an economist at Covenant University in Lagos, told AFP.
"The government is trying all it can and it is going in the right direction in implementing these new policies," he said.
"Nigeria is a huge economy and there are still more opportunities than in many other African countries."
M.Ouellet--BTB