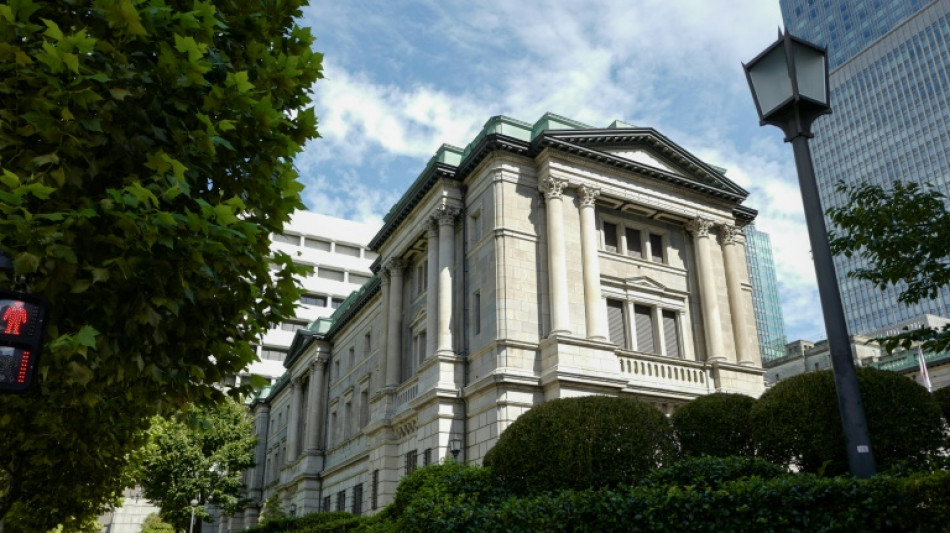
Japan government intervenes to support cratering yen / Photo: © AFP
 England's Nations League surge helps heal World Cup wounds
 Mayor of opposition stronghold Izmir defects to Erdogan party
 Mertens beats Gauff to set up Swiatek clash at China Open
 Benin full of pride at role in Messi's last dance
 France suspends stun grenade use at student protests ahead of PM speech
 Indonesian court hears 'negligence' complaint against state over fires, haze
 Rubio in Greece to urge against Western civilisation 'decline'
 Micron workers at Taiwan plant vote in favour of strike
 In 'The Social Reckoning,' Jeremy Allen White takes on Facebook's 'frightening' ambition
 Chip industry activists call for South Korea to recognise cancer cases
 Famine-scarred southern Madagascar braces for El Nino
 How the EU regulates lobbyists
 I.Coast refuge offers lifelong care for youngsters scorned as 'sorcerers'
 Indian central bank hikes rates for first time in more than 3 years
 Hotel Blacklist Launches New Accommodation Industry Risk Assessment Tool
 Bangladesh nuclear plant draws hope -- and worry
 US beat Canada 1-0 to wrap up four-win international break
 Turkey, Australia's joint COP31 leadership raises doubts
 For Turkish NGOs, COP31 offers rare space for action
 Sleep, appetite, gene-editing experts contend for Nobel chemistry prize
 Nobel Peace Prize haunted by the 'spectre' of Trump
 Africa launches own credit agency in bid for cheaper borrowing
 US, China, EU: three paths to regulating AI
 Australia's High Court rules against coal mine in landmark climate case
 Australia touts new funds for Pacific infrastructure at Fiji 'pre-COP'
Japan's finance ministry said Thursday it intervened in the currency market to bolster the yen, which has plummeted against the dollar in recent months on the widening policy gap between the US and Japanese central banks.
It was the first government intervention to prop up the currency since 1998 and came after the dollar neared 146 yen earlier in the day.
"Although exchange rates are in principle determined by the market, excessive fluctuations caused by speculation cannot be tolerated," Finance Minister Shunichi Suzuki told reporters.
"Based on this, we intervened in the foreign exchange market today. We will continue to monitor developments in the market with a strong sense of urgency and take necessary action against excessive fluctuations," he added.
He declined to detail the scale of the intervention, or its length. And he refused to confirm whether it had been coordinated with Washington or other capitals, saying only he was "in constant contact with relevant monetary authorities".
The move, which involves selling dollars and buying yen, saw the greenback retreat as low as 140.70 before gaining slightly.
Top currency official Masato Kanda told reporters that the intervention was not triggered by the yen falling to a particular level.
"We don't think about the level at all. In principle, (what matters) is volatility."
The yen has been weakening against the dollar for months, but sank further on Thursday after the US Federal Reserve again hiked rates to tame inflation, while the Bank of Japan left its ultra-loose monetary policy in place.
Prices in Japan are rising, with the Consumer Price Index (CPI) rising by 2.8 percent year-on-year in August, the highest level since 2014.
But the central bank views the increases as temporary, and believes its dovish policy is needed to achieve a long-standing target of sustained two-percent inflation -- seen as necessary to turbocharge growth in the world's third-largest economy.
After a two-day meeting, it said it would leave its current policy in place until "CPI exceeds two percent and stays above the target in a stable manner."
- 'Temporary respite' -
A weaker yen has some positive effects, particularly for Japanese exporters, but the recent rapid depreciation has begun to stir concern in Japan, pushing up the cost of imported goods for consumers and businesses.
Earlier this month, the central bank reportedly conducted a "rate check", an operation often seen as a precursor to a currency intervention.
The move came shortly after the yen neared the 145 point, but the reports only temporarily bolstered the Japanese unit.
It has plunged from around 115 in March, and the Bank of Japan (BoJ) on Thursday repeated that "it is necessary to pay due attention to developments in financial and foreign exchange markets and their impact on Japan's economic activity and prices".
But BoJ Governor Haruhiko Kuroda, whose term expires next year, told reporters before the intervention announcement that the bank's role did not extend to moving foreign exchange.
"We haven't been and will not be targeting certain levels of foreign exchange," he said.
"It is desirable that forex rates reflect economic and financial fundamentals, however the recent rapid depreciation of the yen is not that and is negative for the economy," he added.
He noted though that the dollar has gained against most major currencies, and analysts said that the yen's surge after the intervention could prove little more than a "temporary respite".
"Basically the only thing stopping USD/JPY from rising towards 150 is Japanese foreign exchange intervention, but even then it will only be a temporary respite," said Alvin Tan, head of Asia FX Strategy at RBC Capital Markets.
"The yawning policy divergence between the Fed and the BoJ, along with the related widening USD-JPY yield spread, is exerting a powerful and fundamental force, propelling USD/JPY higher," he told AFP, saying he anticipated the dollar breaking 150 yen by 2023.
M.Furrer--BTB