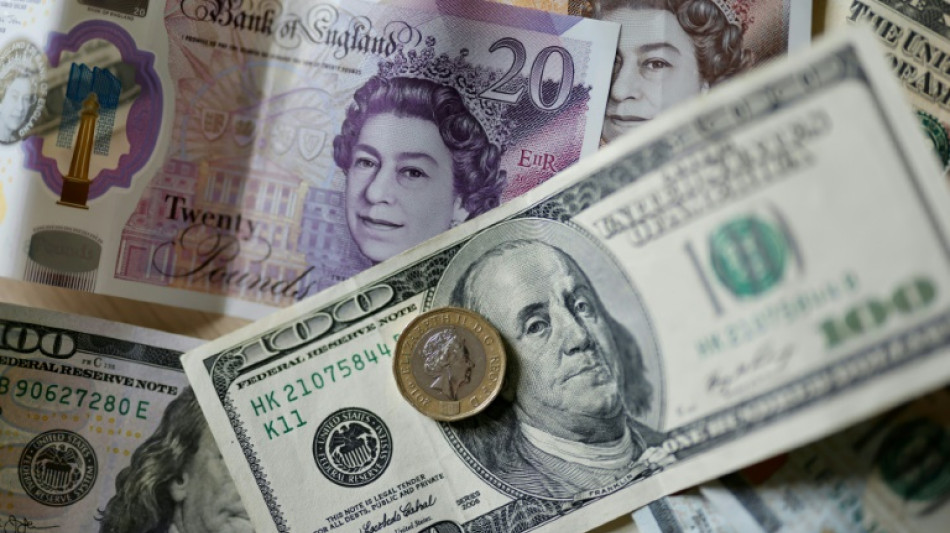
Strong US dollar an unstoppable force endangering other currencies / Photo: © AFP/File
 UK court quashes five ex-traders' Libor rate rigging convictions
 XM Receives “Global Customer Experience Leader Award 2026” at the TrustFinance Performance Awards
 Stocks slide as oil climbs on Mideast flareup
 Heavy casualties in Ukraine after Russian strikes
 French wine harvest set to hit historic low
 Kyiv 'cannot agree' to EU membership limiting food exports: minister
 Arteta targets more Arsenal glory after signing new deal until 2030
 Russell hit with Singapore grid penalty for taking new power unit
 Spotify expands audiobooks to more than 180 markets
 French-Japanese duo wins chemistry Nobel for solving molecular 'mystery'
 England's Nations League surge helps heal World Cup wounds
 Mayor of opposition stronghold Izmir defects to Erdogan party
 Mertens beats Gauff to set up Swiatek clash at China Open
 Benin full of pride at role in Messi's last dance
 France suspends stun grenade use at student protests ahead of PM speech
 Indonesian court hears 'negligence' complaint against state over fires, haze
 Rubio in Greece to urge against Western civilisation 'decline'
 Micron workers at Taiwan plant vote in favour of strike
 In 'The Social Reckoning,' Jeremy Allen White takes on Facebook's 'frightening' ambition
 Chip industry activists call for South Korea to recognise cancer cases
 Famine-scarred southern Madagascar braces for El Nino
 How the EU regulates lobbyists
 I.Coast refuge offers lifelong care for youngsters scorned as 'sorcerers'
 Indian central bank hikes rates for first time in more than 3 years
 Hotel Blacklist Launches New Accommodation Industry Risk Assessment Tool
The dazzling rise of the US dollar, which has hit one record after another, is raising fears of a currency crash of a severity not seen since the 1997 Asian financial crisis reverberated around the world.
The Federal Reserve's rapid, steep interest rate increases and the relative health of the US economy has caused investors to flood into the dollar, driving the greenback up and sending the British pound, Indian rupee, Egyptian pound and South Korean won and others to uncharted depths.
"The moves are definitely getting extreme," said Brad Bechtel of Jefferies, warning that the exchange rates could fall further creating a "dire situation."
Most other major central banks also are forcefully tightening monetary policy to bring down inflation, but so far the moves have not helped stabilized the currency market, nor has Japan's direct intervention to support the yen last week.
Many fear that the same will be the case with the Bank of England's plan announced Wednesday to conduct emergency purchases of government bonds to support the pound.
"We have our doubts that the BoE's plan will be the silver bullet to kill all of the angst that has been pressuring the pound ... considering its plan doesn't have permanency," said Patrick O'Hare of Briefing.com.
Others, especially emerging market countries, are even worse off. The Pakistani rupee has lost 29 percent of its value against the US dollar in the past year, and the Egyptian pound has weakened by 20 percent.
Those countries, and others like Sri Lanka and Bangladesh which "benefitted from cheap and plentiful liquidity," when interest rates were low during the pandemic, "are all suffering from tighter global liquidity," said Win Thin, head of currency strategy at BBH Investor Services.
"Those countries with the weakest fundamentals are likely to be tested first but others may join them," he warned.
Those countries rely on imported oil and grain which have seen prices soar, widening their trade deficits and fueling inflation, massive blows to their currencies.
The appreciation of the US currency has exacerbated the problem, since many commodities are denominated in dollars.
Already in a fragile position, Pakistan was hit with historic flooding in August, which prompted the government to discuss a restructuring of its debt.
"There are severe pressures on the financial system now. And it's only a matter of time until there's a larger crisis somewhere in the world," warns Adam Button of ForexLive.
- Bad memories -
US Treasury Secretary Janet Yellen earlier this week said she has not yet seen signs of "disorderly" financial market developments amid the interest rate hikes.
For countries like Taiwan, Thailand or South Korea, which also dependent on energy imports, China's zero-Covid policy has caused their exports to this key trading partner to plummet.
Larger economies like China and Japan have contributed in recent weeks to the turbulence on the foreign exchange market. The Japanese yen plunged its lowest level in 24 years, while the Chinese yuan hit its weakest in 14 years.
Fear of destabilization brings back memories of the 1997 Asian financial crisis, which was triggered by the devaluation of the Thai baht.
Malaysia, the Philippines and Indonesia followed, which panicked foreign investors and led to massive outflows of capital, pushing several countries into a severe recession and South Korea to the brink of default.
At the time, the collapse of the baht was in part linked to its fixed parity with the dollar, which forced the Thai government to support its currency, depleting its foreign exchange reserves, which was unsustainable in the face of market forces.
Argentina eventually was forced to abandon its peg to the dollar and defaulted in late 2001 -- the largest sovereign default in history.
Erik Nielsen of Wells Fargo said that is a key difference between 2022 and 1997.
"Now there's not a lot of fixed exchange rates," he said. "I'm frankly more worried about developed markets right now."
Lebanon, one of the few to still peg its currency to the greenback, on Thursday announced a drastic devaluation, taking the country's pound to 15,000 to the dollar from the previous fixed value of 1,507.
In the United States, by contrast, where inflation has soared to a 40-year high "the Fed sees strong dollar as a blessing," said Christopher Vecchio of DailyFX, noting that it helps "insulate the economy from more significant price pressures."'
A strong currency means the country pays less for its imported products.
C.Meier--BTB