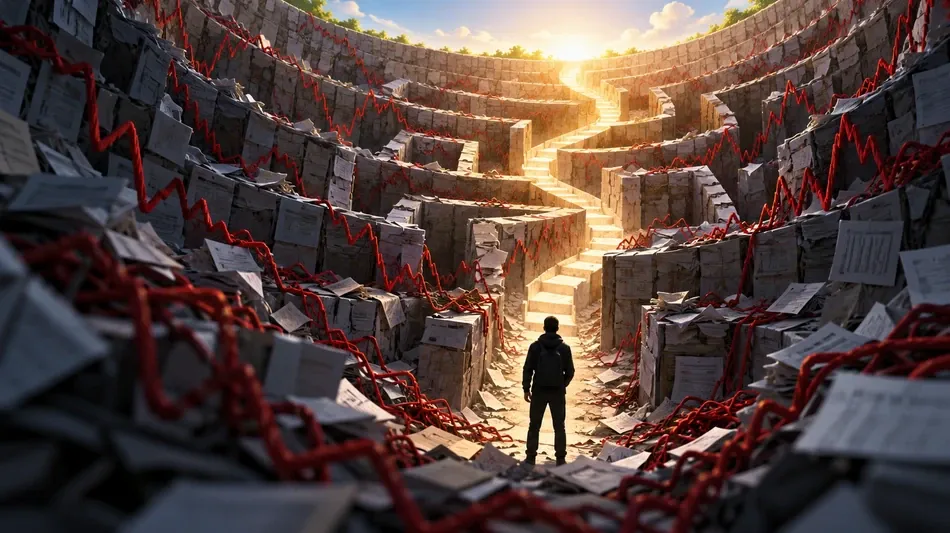
Debt recovery lessons after derivatives losses and repeated borrowing
 Kremlin says Ukrainian attacks won't change war aims as Kyiv hits Saint Petersburg
 Martinez starts for Man Utd after outburst
 Alberta separatists rally ahead of independence vote
 Diesel shortage raises petroleum share of India’s exports to three-year high
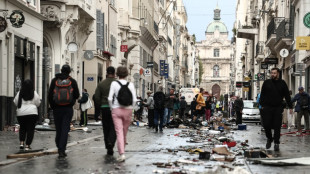
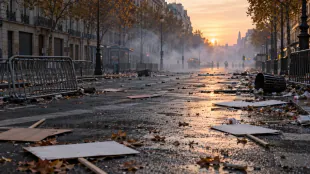 France assesses protest damage after 1,800 arrests
 Gord launches four AI tools for sustainability and emissions management
 Doha 2036 bid sets out sport-led social legacy
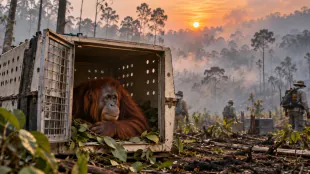 Conservation teams rescue orangutans from Indonesian wildfires
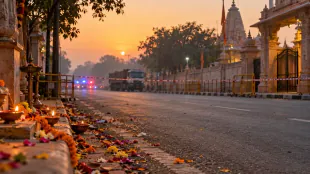 Truck ploughs into Hindu festival crowd in India, killing 13
 Kuwait announces maintenance closures in Nuzha, Surra and Rai
 Moody’s lifts OYO parent Prism outlook to positive before planned IPO
 RCom professional asks Supreme Court to revisit spectrum insolvency ruling
 Debt recovery lessons after derivatives losses and repeated borrowing
 Katie Alexander reportedly leaves flat shared with Eamonn Holmes
 Body found in search for missing Glasgow teenager
 Andi King recounts late-life transition after decades behind an “alpha male” identity
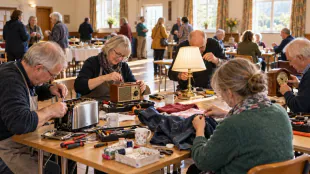 Bromsgrove Repair Cafe reports nearly 80% repair success rate
 B.C. Lions focus on playoff momentum after Calgary defeat
 Tata Trusts plans network of 40 to 50 not-for-profit hospitals
 Bajaj Finance set to report second-quarter results on October 19
 Messi reaches 936 career goals after Inter Miami brace
 Indian petrol and diesel prices remain unchanged on October 18
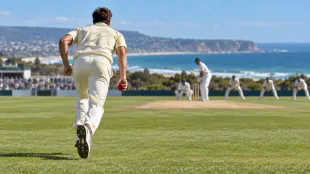 Australia elect to bowl against South Africa in second Test
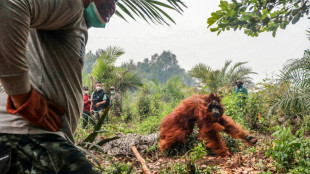 Dozens of orangutans saved from Indonesia blazes as region grapples with haze
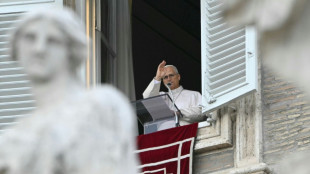 Pope addresses crowd in Vatican after cancer surgery
A personal account of losses in futures and options trading outlines how repeated borrowing deepened a debt crisis and why recovery required a structured repayment plan rather than further trades.
A personal account of losses in futures and options trading outlines how repeated borrowing deepened a debt crisis and why recovery required a structured repayment plan rather than further trades.
When you have one loan, you may think you have a financial problem. When you have several loans, the problem becomes much more complicated.
That was my situation. I was not dealing with one lender and one EMI. I was dealing with many at once: a credit-card outstanding, personal loans, money borrowed from friends and relatives, and money from private sources at a very high rate of interest.
Each had its own interest rate, due date and EMI. As one date passed, another was already approaching. The pressure never really switched off.
I had to figure out which debts to prioritise, how to manage repayments when my income fell short, and how to stop one debt from creating another. This is what I learnt from the experience.
This is how I tried to answer them. It is not advice — only what happened to me, and what I learnt.
THE FIRST QUESTION: WHICH DEBT DO I PAY FIRST?
At first I told myself the answer was simple: repay everything. But “everything” is not a plan. With several debts running at once, it only made me feel their combined weight.
So I stopped looking at the debt as one mountain and looked at each debt separately. For every one, I wrote down:
● How much I owed, and to whom
● The interest rate
● The principal outstanding
● Penalties and charges
● How quickly it was growing
● Whether it could be negotiated or restructured
● Whether the lender was a bank, a financial institution, a friend, a relative or a private lender
Before I could repay anything, I had to understand the full picture and make decisions based on numbers rather than fear.
How I Prioritised My Debts
Once I could see everything, I stopped treating all debt as equal. A rupee owed to a card issuer, a bank, a friend and a private lender is not the same problem, and I approached each differently.
Credit Cards
Carrying a balance can be very costly, and it grows quietly. So I contacted the card issuer to understand the exact outstanding and the repayment options. Where appropriate, I explored restructuring or settlement, but I learnt to understand the consequences before agreeing to anything; settlement depends on the issuer and may affect my credit record.
And I would not take another expensive loan to clear a card.
Personal Loans
Personal loans I looked at one by one: outstanding principal, interest rate, EMI, remaining tenure, and the pressure each EMI placed on my monthly cash flow. I would rather speak openly to the lender and understand the possibility of restructuring or a revised schedule than avoid the problem. Whether such options exist depends on the lender and one’s circumstances, but asking early leaves more room.
Friends And Relatives
One of the hardest conversations for me was not with a bank. It was with people I knew personally. Money borrowed from friends and relatives carries something no loan agreement does: trust.
There was embarrassment in admitting I could not repay immediately, and a constant temptation to avoid the call. But silence only made it worse. I learnt to speak honestly, acknowledge what I owed, give a realistic timeline instead of a comforting one, and avoid promises I could not keep.
A broken promise costs more than a delayed payment.
High-Interest Private Borrowing
I calculated the actual principal, the accumulated interest and the exact repayment obligation, then spoke to the lender and tried to negotiate a realistic arrangement where possible. Where the situation was complicated or legally sensitive, I learnt it was wiser to take professional or legal advice than to guess. The aim was to understand and control that debt, never to cover it with another one.
When My Income Did Not Cover The Repayments
Underneath all of this was a harder truth: my income was not enough for every repayment to be comfortable. I protected the essentials first — housing, food, education, insurance, medical expenses, my ability to keep earning — then looked at reducing spending, using savings carefully and selling any non-essential asset. A smaller plan I could sustain, built on income I could rely on, was worth more than an aggressive one that would collapse in two months.
THE MOST DANGEROUS CYCLE: DEBT TO REPAY DEBT
That gap brought the most dangerous temptation of all: solving a repayment with new borrowing. Debt creates repayment pressure, pressure creates new borrowing, new borrowing creates a new debt, and that creates more pressure. One credit card used to pay another.
A new loan taken to meet an old EMI. Money borrowed from one person to repay another. High-interest money taken to clear another high-interest obligation.
Then came the moment I understood what was really happening: I am no longer solving the debt. I am simply moving the debt from one place to another. I had created the illusion of managing it while only relocating it, often somewhere more expensive.
Genuine consolidation can help, in my understanding, if it lowers the total cost and gives a realistic plan. New expensive borrowing without one is the same debt in a different disguise.
The Weight I Carried
Debt is not only a financial problem. It lives in the mind. I thought about repayments constantly.
I feared missed payments. My heart sank whenever the phone rang, and I began avoiding conversations. There was shame, stress and a slow loss of confidence, and it became hard to concentrate on anything else.
With several people and institutions waiting for repayment, it felt as though the debt followed me everywhere.
I learnt that shame is the most expensive emotion in debt: it makes you avoid exactly the conversations that could help. None of it looked dramatic from outside.
The Moment I Realised I Had To Stop
For a long time, I kept asking how I could make more money. Eventually, the question changed to how I could get out of the situation. Accepting the full amount did not reduce the debt by a rupee, but it helped me think clearly for the first time.
The Market Was Never A Repayment Plan
There was one more thing I had to admit. For a long time I had allowed myself to believe the market could solve this: one good trade can change everything. That thought is dangerous.
If I need a market profit to pay tomorrow’s EMI, the trade is no longer simply a trade. It has become a financial necessity, and once a trade becomes a necessity, emotional decision-making becomes far more likely. I cannot use tomorrow’s market profit to pay today’s EMI.
The market did not know I had borrowed, or my EMI, or my card due date.
The Part Of The Story I Have Not Yet Told You
There is one important part of this story I have not yet told you: how did I get into this debt in the first place?
It began with F&O trading. My first few trades worked, and the early profits gave me a confidence more powerful than the money itself. Then the losses came, and with them the wish to recover.
I took greater risks, because each loss raised the target for the next trade. Eventually my own capital was not enough, and borrowing entered the picture: a loan, then another, then credit cards, then money from other sources. Every rupee carried the same silent justification: one good trade will recover everything.
The market did not know I had borrowed, or my EMI, or my card due date. When borrowed money was lost, I no longer had a trading problem. I had a debt problem.
The Real Lesson I Learnt
Looking back, the lesson is not simply that F&O is risky. The real danger began when I used borrowed money to try to recover money I had already lost.
Losing my own surplus capital hurts, but it ends where the capital ends. Borrowing changes the nature of the risk, because an obligation is now attached. Losing borrowed money turns a trading loss into a repayment.
And borrowing again to recover the borrowed money is where the cycle turns dangerous: I was no longer taking a market risk, I was gambling with money that was not mine.
What I Would Tell Myself Today
If I could go back, I would tell myself that the way out is never another trade. What my experience taught me is that it was accepting the debt, listing it, prioritising it, speaking to the people and institutions I owed, managing my cash flow and rebuilding gradually. I would never again use borrowed money to chase a loss.
The biggest lesson for me was not how to recover a trading loss. It was how to stop the cycle and rebuild my financial life.
There will always be another trade. There will always be another expiry. But when financial stability is lost, the market cannot guarantee that it will give it back.
Sometimes the most profitable decision a trader can make is to stop trading and start rebuilding.
The fact that it took many years to rebuild and that I now have a respectable life and decent net worth is an important personal payoff.
I got there by not losing hope and by following a proper plan, patiently, one month at a time. So if you are in debt, do not lose hope. All you have to do is make a proper plan, and then keep following it.
J.Bergmann--BTB